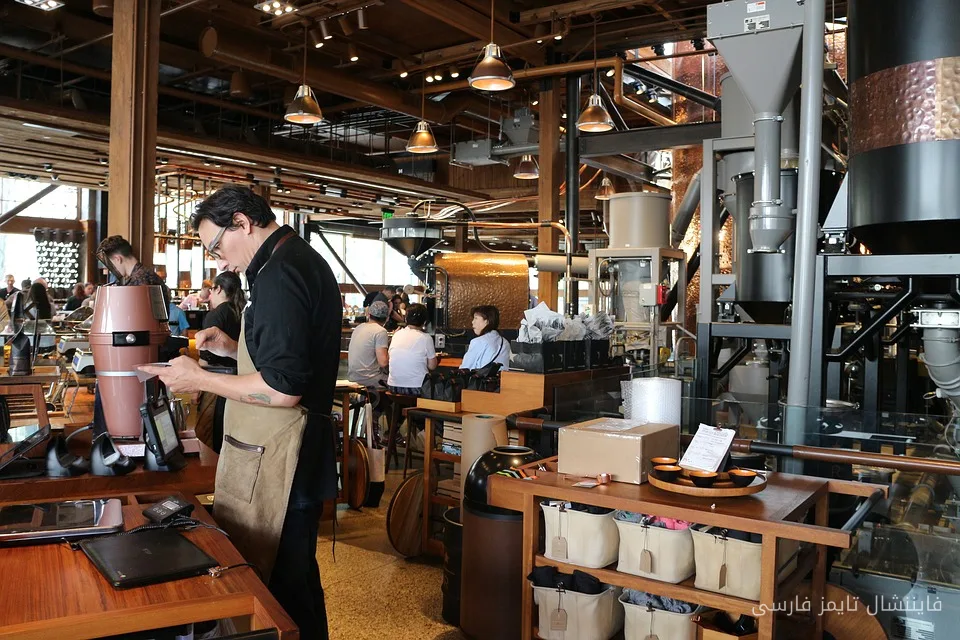
Starbucks (NASDAQ:SBUX) is investing one billion dollars to renovate over 9,000 of its stores in North America to create a warmer and more inviting space for customers. This initiative is part of the "Return to Starbucks" strategy led by Brian Niccol, and its goal is to attract customers who have been visiting less due to changes in the store environment.
Renovation Details and Financial Impacts
The renovation includes the installation of leather seating, carpets, and bookshelves, with the average cost per store estimated at $150,000, significantly lower than previous renovation costs. Starbucks hopes to renovate about 1,500 stores by the end of September and ultimately achieve its goal of renovating 8,000 to 9,000 stores. These changes come as stores have increasingly been optimized for transactions, with mobile orders now accounting for about one-third of transactions in the U.S.
Read more: New Hope's output growth in FY26 led to a 33% return for shareholders
Challenges and Opportunities Ahead
While renovated stores are likely to attract more customers and encourage them to spend more, the key question is whether these changes will be able to increase profit margins. While Starbucks has projected an increase in its revenues for fiscal year 2026, reaching earnings per share between $2.55 and $2.65, global operating margins have decreased to 12.9%, a significant drop from 15.8% two years ago.
This renovation trend comes at a time when Starbucks is facing increasing competition from fast-casual coffee chains like Dutch Bros and 7 Brew, which emphasize speed and convenience. At the same time, independent cafes focus on atmosphere and community. Starbucks is trying to respond to both segments while not missing out on the advantages of modern business.
Given these developments, Starbucks' substantial investments in store renovations can be seen as a positive move, but the ultimate success depends on the company's ability to increase customer traffic and improve profit margins. Currently, Starbucks' stock appears to be trading at a price-to-earnings (P/E) ratio of about 38.29, above its five-year average, indicating the need for the company to improve its financial performance to justify this high valuation.
Read more: The Bank of Finland predicts higher growth and lower unemployment · White Cliff Minerals' stock price rises with Hancock Prospecting investment